The Best European Cities for Airbnb Investments
Last updated: October 19, 2026
- Key Takeaways
- Why Europe’s Airbnb Map Changed in 2026
- City Evaluation Methodology for Airbnb Investment
- The Best European Cities for Airbnb Investments
- Cities Where Airbnb Is Legal in 2026
- Best Countries for Airbnb Investment in Europe
- Risks and Challenges for Airbnb Investors in Europe
- FAQ
- Final Words
Key Takeaways
- The best place to buy Airbnb property in Europe in 2026 is wherever you can still register a new short-term rental, because several headline markets have closed their registries to newcomers.
- Madrid, Athens and Budapest each restrict new short-term rental flats by a different route, from Madrid’s historic-centre zoning to Budapest’s city-wide freeze, so none belongs on a standard buy-side shortlist.
- A typical listing in the twelve markets below earns roughly €15,500 to €51,000 a year, cleaning fees included. Set against a 50 m² central flat, that revenue ranges from about 6% of the price in London to about 22% in Palermo, which is a rough screen rather than a return.
- Lisbon deserves special care: inside the city’s containment zones, selling the property generally cancels its Alojamento Local registration, so a licensed flat does not come with a transferable licence.
- Regulation (EU) 2024/1028 has applied since 20 May 2026, so wherever a registration procedure applies, platforms must collect the number, display it and spot-check it.
- Investors reduce risk by favouring flexible locations, keeping a backup medium- or long-term rental plan, and using conservative financial assumptions.
Why Europe’s Airbnb Map Changed in 2026
The best place to buy Airbnb property in Europe in 2026 is a market that still registers new hosts. On current figures, Palermo and Malta show the most revenue relative to entry price. Rome earns the most among large cities without a night cap, and Valencia sits between the two. Each comes with conditions covered below. Madrid, Athens, and Budapest restrict new registrations where investors usually look, and a headline daily rate is worth nothing if you cannot legally use it.
This guide speaks to private investors, property owners, and people thinking about buying a short-term vacation rental in Europe. It shows how to look at demand, risk, and numbers, not only at pretty streets and high nightly rates. You will find main selection criteria, a practical list of cities, a regulatory map, and key risks that can affect profitability and yield.
Two changes drive most of what follows. First, Regulation (EU) 2024/1028 has applied across the EU since May 2026. Wherever a registration procedure applies, platforms must now display and check the number. Second, national and municipal rules moved in opposite directions, with Portugal loosening its national framework while Lisbon tightened its own.
The text is for information only and does not constitute financial, tax, or legal advice. You should always check local rules, taxes, and personal investment plans with qualified experts before you act.
City Evaluation Methodology for Airbnb Investment
Tourism Demand and Seasonality
First, we look at tourism demand and seasonality. Stable flows of visitors, events, and business travel mean more months with good occupancy and fewer empty weeks. Strong summer-only markets can work, yet they need higher margins and careful cash flow planning.
Average Daily Rates and Occupancy
Second, we check average daily rates, pricing, and occupancy together. A high ADR with many empty nights can bring less income than a mid-price city with steady booking volume. Therefore, we focus on yearly revenue per unit, not just the headline “price per night” in ads. If you want to run these numbers yourself before you commit, our roundup of Airbnb statistics services covers the tools that publish them.
Local Regulations and Compliance
Third, we review regulation and future risk. Cities may require a license, cap annual nights, or limit short-term use to a primary home or specific neighbourhood. Without full compliance, clear permits, and respect for local legislation, a host risks fines or a forced move to long lets.
In 2026 this criterion outranks the others. A market that has frozen new registrations is not a weak buy. It is not a buy at all, because the asset cannot legally produce the revenue your spreadsheet assumes.
Property Prices and Acquisition Costs
Fourth, we look at property prices, buying costs, and finance. Central apartment or condo prices can be far higher than outer districts, even in the same location. On top of this, buyers must count purchase taxes, legal fees, registry charges, and often higher mortgage rates for foreign investors.
Taxes, Expenses and Management
Fifth, we consider taxation, normal expenses, and day to day management. Net rental results depend on income tax, city tourist taxes, utilities, maintenance, cleaning, linen, repairs, and platform fees. You should also budget for a manager or co-host if you cannot be present in person.
Target Guests Profile and Strategy
Finally, we define the main guest profile in each market and match it with a clear strategy. Some areas work best for weekend couples, others for families, digital nomads, or corporate stays. Their needs shape unit size, amenities, hosting style, and the way you manage your calendar and avoid vacancy.
Taken together, these factors help us compare the best European cities for Airbnb investments in a structured way instead of chasing hype.
The Best European cities for Airbnb Investments
We focus on cities that mix strong demand, realistic rental returns, and a registry that is still open to new hosts. The list of the best European cities for Airbnb is not exhaustive and is not a direct “buy this building” guide. It is a starting point for your own on-the-ground checks and deeper analytics.
For each city you will see a short overview, a note on property types and areas that often work well, a brief rules summary, plus main benefits and risks for the investor. Madrid, Athens, and Budapest do not appear. Each has stopped accepting new registrations in the areas investors target, and the next section sets out what they did.
Short Overview of the Top European cities for Airbnb Investments
Demand figures are Airbtics market estimates for the twelve months to August 2026. Airbtics describes them as medians across all listing sizes, and its revenue figure includes cleaning fees. Purchase prices come from Numbeo’s city-centre apartment benchmark, read in October 2026, and the entry price assumes a 50 m² one-bedroom unit. For Malta, revenue covers Airbtics’ Malta market, and the price is Numbeo’s national city-centre average.
The last column divides revenue by that entry price. The two figures describe different properties. Treat the ratio as a rough screen for where revenue runs high relative to price, not as a yield you can expect. The table is sorted by annual revenue.
| City | Occupancy | ADR | Annual revenue | Entry price, 50 m² central | Revenue ÷ 50 m² price |
| London | 71% | €191 | €50,526 | ~€837,000 | ~6.0% |
| Rome | 76% | €160 | €45,936 | ~€369,000 | ~12.5% |
| Valencia | 79% | €131 | €38,846 | ~€247,000 | ~15.7% |
| Malta (national) | 77% | €130 | €37,496 | ~€196,000 | ~19.1% |
| Milan | 68% | €142 | €36,525 | ~€477,000 | ~7.7% |
| Lisbon | 76% | €122 | €35,125 | ~€343,000 | ~10.2% |
| Prague | 78% | €114 | €33,429 | ~€414,000 | ~8.1% |
| Porto | 73% | €98 | €27,185 | ~€229,000 | ~11.8% |
| Palermo | 68% | €99 | €25,373 | ~€117,000 | ~21.6% |
| Kraków | 75% | €89 | €25,333 | ~€247,000 | ~10.3% |
| Warsaw | 67% | €84 | €21,705 | ~€271,000 | ~8.0% |
| Bucharest | 64% | €64 | €15,542 | ~€168,000 | ~9.2% |
One warning before you use that table. London’s revenue figure is a median across every listing type and includes cleaning fees. A whole home in Greater London can be let short-term for only 90 nights a year without planning permission for a change of use. At the city’s average nightly rate, 90 nights brings in about €17,000 of accommodation revenue, roughly 2% of the entry price before costs.
Lisbon (Portugal)
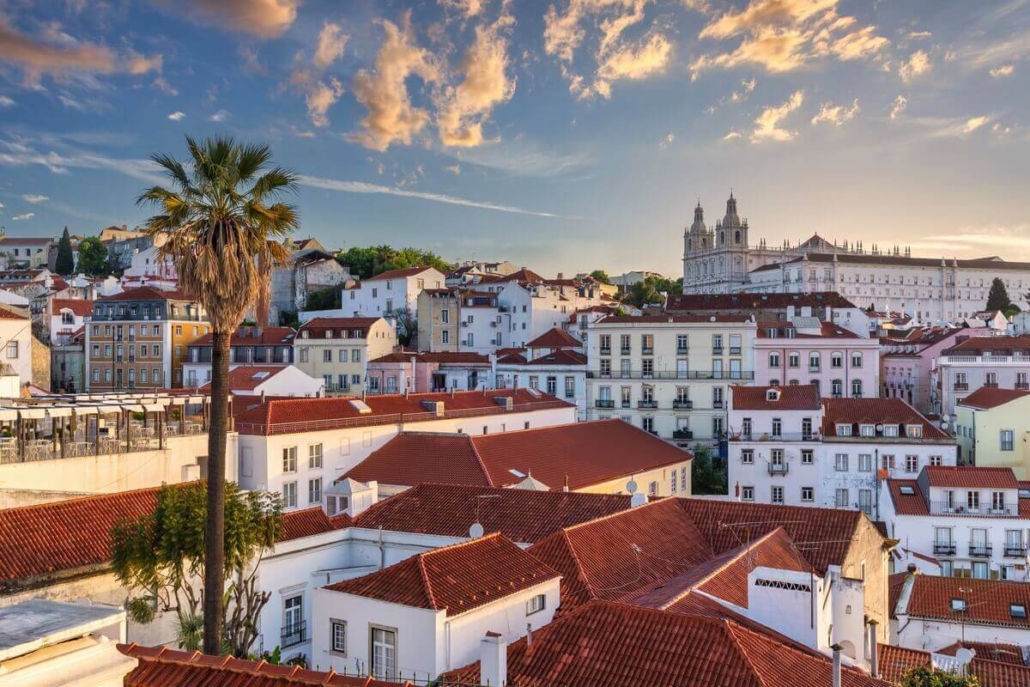
Lisbon remains one of the best European cities for Airbnb investments because demand stays strong most of the year. Average occupancy sits at about 76%, ADR is around €122, and a typical listing earns roughly €35,000 in annual revenue.
Areas hosts commonly target include Baixa & Chiado, Alfama & Mouraria, Bairro Alto & Cais do Sodré, plus Príncipe Real and Graça. Small apartment units, mainly studios and 1 to 2 bedroom flats, are the usual stock in these neighbourhoods.
Now the part that changes the investment case. Lisbon’s amended Alojamento Local regulation took effect on 6 December 2025. Parishes where short-term rentals reach 10% or more of permanent homes fall into absolute containment, and those between 5% and 10% into relative containment. In both, transferring the property as a rule cancels the AL registration for apartments and houses, with narrow exceptions such as inheritance.
Read that twice if you are buying: an “AL licensed” flat in a containment zone does not hand you a working licence at completion. Six parishes started in absolute containment, with no new registrations: Santa Maria Maior, Misericórdia, Santo António, São Vicente, Arroios and Estrela, plus nine smaller neighbourhoods. Every area named above sits inside one of them. In relative zones, a new registration needs exceptional authorisation. Check the current map, the seller’s registration and the deal structure before you sign.
Benefits for investors
- Strong year-round tourism and high occupancy
- Premium pricing in the historic core
- Liquid resale market for central units
- Registrations no longer expire after five years under the national rules
Risks for investors
- AL registration generally lapses on sale inside containment zones
- No new registrations in six central parishes, including the whole historic core
- Intense competition and rising purchase prices
Porto (Portugal)
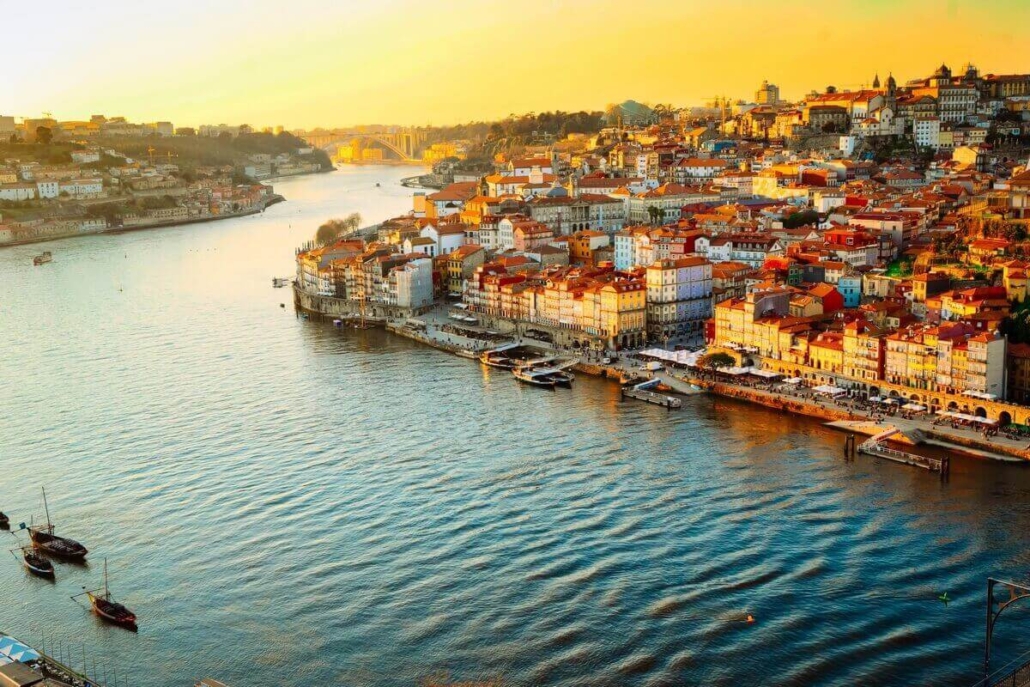
Porto is a strong short term rental market in the north of Portugal. In 2026 it is also the easier Portuguese entry point of the two. Average occupancy runs at about 73%, ADR is close to €98, and a typical listing earns about €27,000 per year. Demand peaks in summer but spring and early autumn also perform well, so seasonality is noticeable but manageable.
Areas hosts commonly target include Ribeira, Baixa and Aliados–São Bento, Cedofeita & Clérigos, Bonfim and Miragaia. The riverfront across the Douro belongs to Vila Nova de Gaia, a separate municipality with its own rules. Studios and 1 to 2 bedroom apartments work best, especially those with river views or easy access to the historic centre.
Porto applies a 15% containment threshold. Five historic-centre parishes are closed to new registrations, save narrow exceptions: Vitória, São Nicolau, Sé, Santo Ildefonso and Miragaia. Bonfim, by contrast, still had room under its cap in July 2026, though quotas move, so check the live municipal map. National rules restored in November 2024 let a registration survive a sale. The exception is a containment area where the municipality limits transfers. Lisbon has done so; Porto’s published regulation does not appear to, though a buyer should confirm with the Câmara.
Benefits for investors
- No Lisbon-style transfer limit found in Porto’s published rules
- Strong wine, riverfront and culture brand
- Mix of leisure and weekend city-break demand
- Lower entry prices than Lisbon for similar guest appeal
Risks for investors
- Five central parishes already closed to new AL registrations
- Growing competition and pressure on design and reviews
- Seasonal dips in winter that raise vacancy risk
- Rising purchase and operating costs over time
Valencia (Spain)
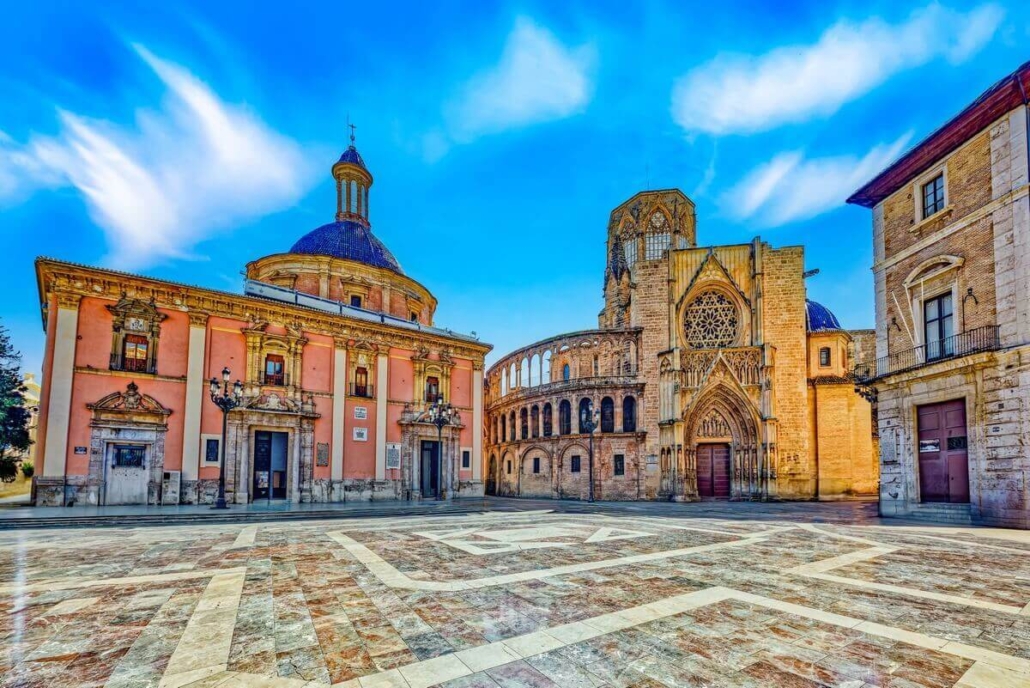
Valencia shows the highest revenue relative to entry price of any mainland city here. Occupancy runs at roughly 79%, ADR is near €131, and annual revenue is close to €39,000 against a central entry price around €247,000. Areas hosts commonly target include the Ensanche (L’Eixample), with Ruzafa inside it, and El Carmen in the old town.
That number comes with a cap city officials describe as the most restrictive in Spain. Rules approved by the city council on 31 March 2026 hold tourist homes to 2% of the housing stock in each neighbourhood and district. Total tourist beds, hotels included, are capped at 8% of an area’s registered population. No more than 15% of a block’s ground-floor premises may hold tourist accommodation. New flats must also sit on the ground or first floor of a mixed-use building, with independent street access and no homes on the same landing. Ciutat Vella follows its own special plan.
On 19 May 2026 Spain’s Supreme Court annulled the parts of Royal Decree 1312/2024 that created the national single registry. Regional licences and municipal rules remain the real gatekeepers. Since 3 April 2025, a new tourist flat in a Spanish apartment building also needs community approval. Three fifths of the owners, holding three fifths of the shares, must vote for it. In practice, a Valencia purchase depends on the local cap, the building’s layout and a community vote.
Benefits for investors
- Highest revenue relative to entry price of any mainland city here
- Good balance of city and beach tourism
Risks for investors
- Neighbourhood-level caps can close your target street before you complete
- Owners’ community approval needed for a new tourist flat
- Clear summer seasonality
- Regional rules still settling after the Supreme Court ruling
Prague (Czech Republic)
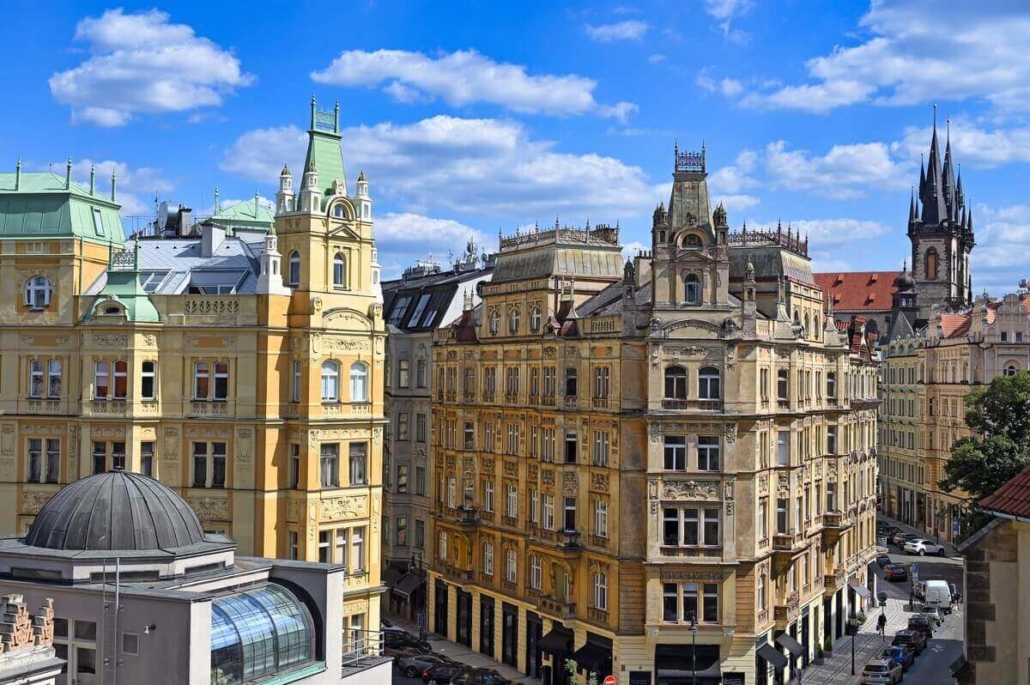
Prague belongs on any list of profitable European cities for Airbnb, thanks to steady tourist traffic and strong numbers. A typical listing reaches about 78% occupancy, with an ADR near €114 and roughly €33,000 annual revenue, and August usually brings the highest demand. Districts hosts commonly target include Karlín, Smíchov, Vinohrady, and Holešovice.
Compact studios and one-bedroom apartments near tram and metro stops work well for couples and small groups. Local rules remain comparatively relaxed, though that is a statement about today rather than about 2028. The Czech Republic is preparing eTurista, a national register meant to fold guest reporting and tourist tax filing into one system. It would give every unit a registration number to show in its listings. Rollout has slipped more than once, and a draft amendment proposes 2028, so check its status before building it into a plan.
Prague 1, the historic core, has pushed publicly for stricter treatment of short-term rentals through that system. Prague also sits near the bottom of the revenue-to-price table, because central prices run above Rome’s while revenue sits well below it.
Benefits for investors
- High volume of year-round city-break visitors
- Strong occupancy and mid-scale daily rates
- Variety of central neighbourhoods with different price points
Risks for investors
- eTurista registration is coming, with timing still unsettled
- Prague 1 is lobbying for tighter central rules
- High central purchase prices compress yield
- Wear and tear from party tourism
Krakow (Poland)
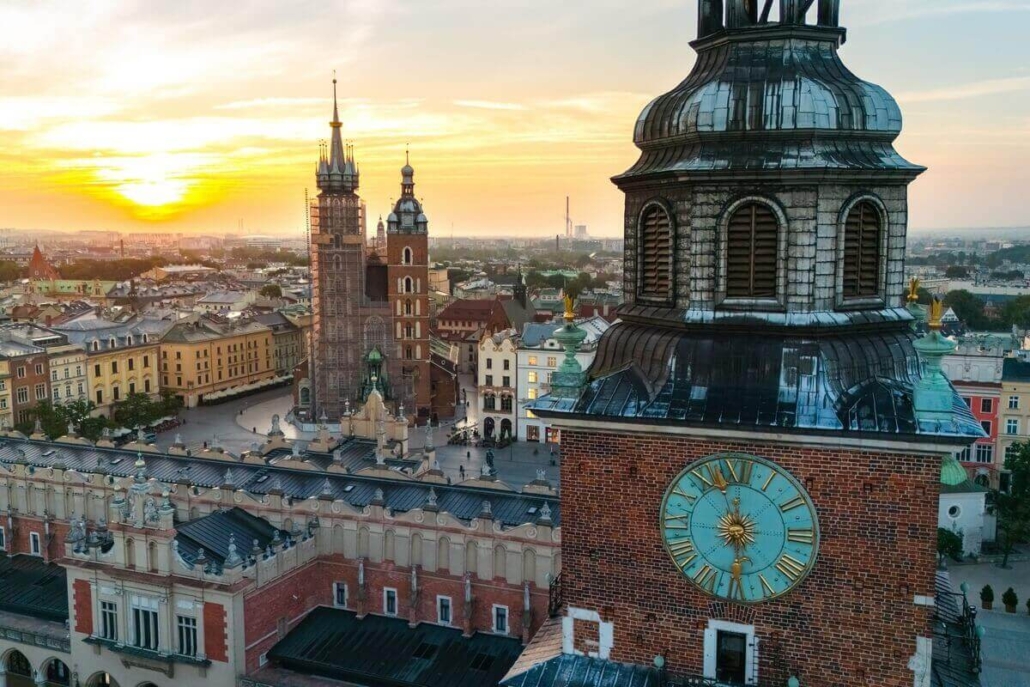
Kraków is a classic city-break destination and offers genuine value among the best European cities for Airbnb investments. A typical listing runs at about 75% occupancy, €89 ADR and around €25,000 annual revenue. Hosts commonly target studios and 1 to 2 bedroom apartments near Main Market Square, Wawel and Planty Park, along with character units in Kazimierz and Podgórze.
Poland has had some of the lightest rules of the markets here, and that is changing. On 8 October 2026 the Sejm passed a law that, for the first time, regulates short-term rentals directly. It treats stays of up to 30 days as a hotel service. Under the bill, every unit would have to be registered and show an identification number in its listings. It still needs the Senate and the President, and proposed fines reach PLN 50,000 for renting without a number.
One provision sits further out and deserves pricing in now. From 1 January 2028, housing communities, cooperatives and municipal councils could ban short-term rentals in a building or an area. A whole building would sit outside a condominium vote, but not outside a municipal zone, so check both.
Benefits for investors
- Solid leisure tourism across most of the year
- Attractive entry prices compared with Western Europe
- Strong backup demand for long-term rental from students and expats
Risks for investors
- Condominium and municipal bans proposed from January 2028
- Registration and listing-number duties proposed in the new bill
- Extra wear and tear from party and group stays
- Currency and Polish rental taxation rules to navigate
Warsaw (Poland)
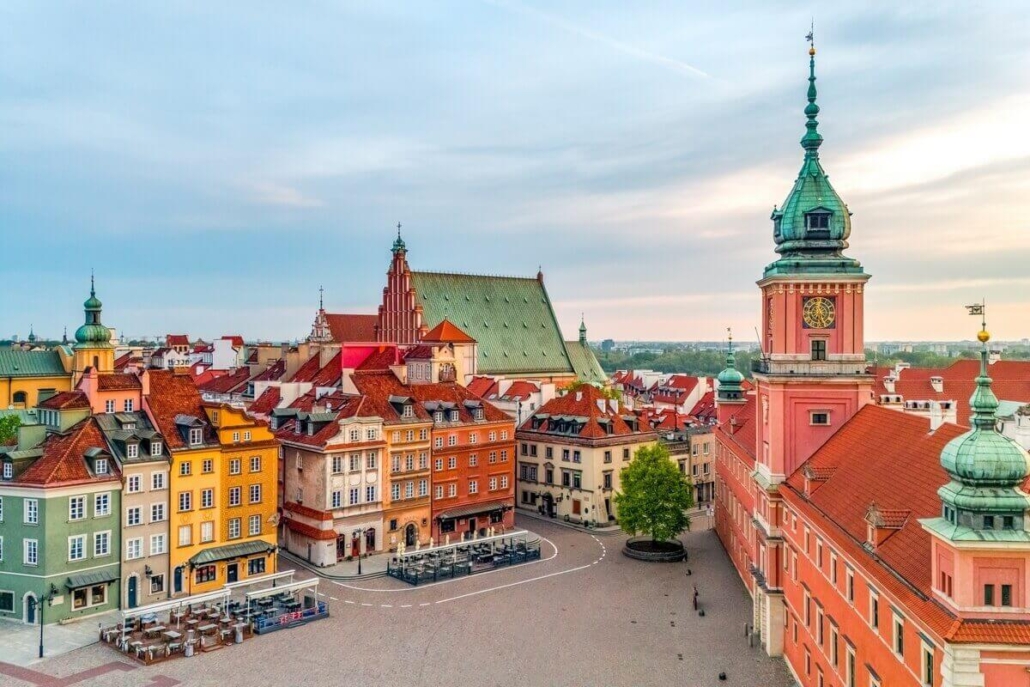
Warsaw suits investors looking for growth rather than headline yield. A typical listing runs at around 67% occupancy, an ADR close to €84, and roughly €22,000 in annual revenue. Demand peaks in August, yet business travel and events help support bookings through the rest of the year.
Strong areas for a vacation rental include Śródmieście, Wola, and Białołęka. Studios and 1 to 2 bedroom apartments near metro lines attract both tourists and business guests. The national legislation described above applies here too, so the proposed registration duty and 2028 ban powers belong in any Warsaw underwriting.
Warsaw sits near the bottom of this group on occupancy, and that matters more than the modest ADR. Corporate demand helps midweek. Still, selling 67% of available nights leaves plenty of unsold capacity at a thinner nightly rate.
Benefits for investors
- Healthy mix of corporate and leisure demand
- Moderate purchase prices for a capital city
- Solid long-term rental fallback if short-term rules tighten
Risks for investors
- One of the lowest occupancy rates in this guide
- Condominium and municipal bans proposed from January 2028
- Strong competition in central streets
- Currency and Polish tax rules to manage
Rome (Italy)
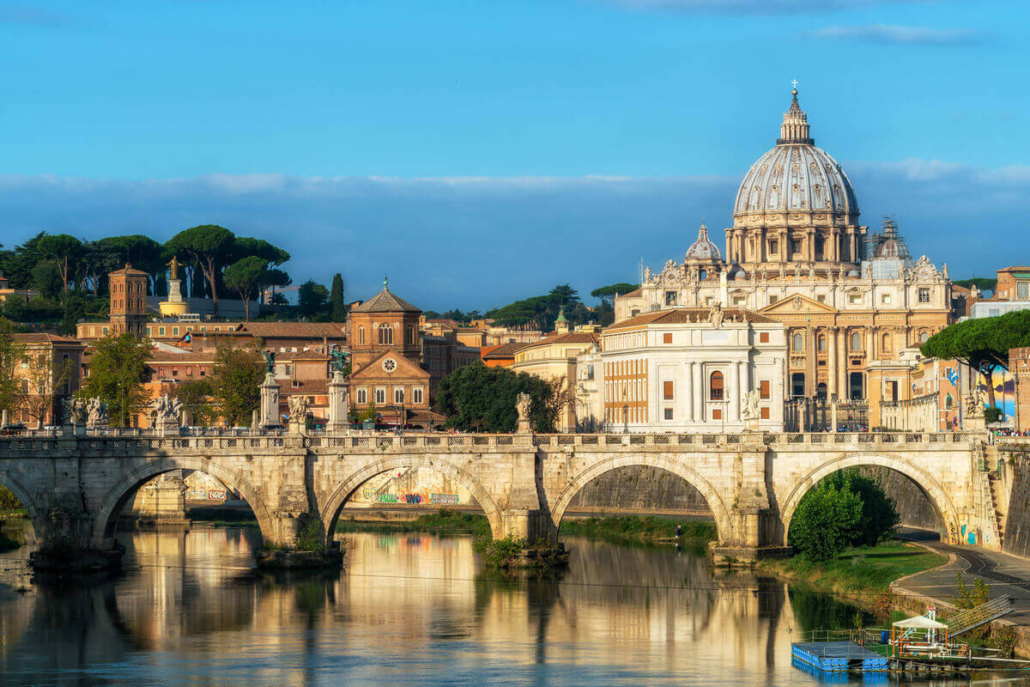
Rome is one of the most mature Airbnb markets in the EU. Once London’s night cap is taken into account, it is also the strongest large city in this guide. A typical listing runs at 76% occupancy, with an ADR around €160 and roughly €46,000 annual revenue.
Zones hosts commonly target include Municipio I and Municipio II around the historic centre, Via della Stazione Tuscolana, and Municipio XIII around Aurelio, just west of the Vatican. Compact studios and 1 to 2 bedroom apartments near metro lines and monuments attract short-term guests.
Italy’s core compliance rules are national, though regional and municipal rules sit on top. Every tourist rental has needed a CIN, the national identification code, since 1 January 2025 under Article 13-ter of Decree Law 145/2023. It must appear at the property and in every advert. Fines run from €800 to €8,000 for operating without one, and €500 to €5,000 for not displaying it. Since a November 2025 Council of State ruling, hosts must also confirm in person that the guest matches the ID submitted, or use live video at the entrance. An unattended key box no longer suffices.
Model tax early. Since 1 January 2026, the cedolare secca flat rate is 21% on the first short-term rental property and 26% on the second. From the third apartment let short-term in a tax year, the whole activity counts as a business, down from more than four before.
Benefits for investors
- Global destination with very strong tourism
- High nightly rates in central neighbourhoods
- Deep resale market for well-located apartments
Risks for investors
- Registration, safety equipment and in-person identification duties
- Heavy competition in the historic core
- Higher purchase prices and running costs
- Business-activity threshold now starts at three properties
Milan (Italy)

Milan is the business capital of the Italian market and one of its deepest. A typical listing runs at about 68% occupancy, with an ADR around €142 and roughly €36,500 in annual revenue. Demand rests on trade fairs, fashion weeks and corporate travel as much as on tourism, and the city co-hosted the 2026 Winter Olympics.
Brera, Navigli, Porta Romana, Isola and the streets around Centrale station are the usual short-stay zones. One-bedroom flats close to a metro stop suit business guests best.
We found no city cap on new short-term rentals in Milan. Instead, from January 2026 it banned key boxes on public land, such as road signs and lamp posts. The ban also covers private structures facing public ground, such as building entrances and gates. Fines run from €100 to €400 plus removal costs. Together with the national in-person identification rule, that pushes hosts towards staffed check-in or live video at the door.
The catch is price. At roughly €9,500 per m² in the centre, a 50 m² unit costs about €477,000. That puts Milan’s revenue at about 7.7% of the entry price, the lowest ratio here after London.
Benefits for investors
- Year-round business and event demand
- No city cap on new short-term rentals found
- Large, active property market
Risks for investors
- Second-highest entry price in this guide, which compresses yield
- Key-box ban and in-person ID checks raise operating costs
- Event-driven pricing makes the calendar uneven
Palermo (Italy)

Palermo is the value surprise of this guide. A typical listing runs at about 68% occupancy, with an ADR near €99 and roughly €25,000 in annual revenue, against a central entry price of about €117,000. That puts revenue above 21% of the entry price, the highest ratio here. One caution: Numbeo’s Palermo price rests on a small sample, so treat the entry figure as rough and get local valuations.
Hosts commonly target the historic centre, around the Kalsa, Via Maqueda and Teatro Massimo, and the Politeama and Libertà districts for quieter stays.
The rules are Italy’s national framework plus a regional layer. Besides the CIN, Sicily has required its own regional identification code, the CIR, for short-term rentals since 2022, and the code must appear in listings. Its 2025 regional tourism law then redrew the accommodation categories and filings. We found no city-level cap on new short-term rentals in Palermo as of October 2026. That is a limited finding, not a guarantee that any given flat qualifies. The national in-person identification rule and the three-property business threshold apply here too.
Benefits for investors
- Lowest entry price and highest revenue-to-price ratio in this guide
- No city-level cap on new short-term rentals found
- Italian national rules, with the CIN regime already bedded in
Risks for investors
- Thin price data and a less liquid resale market
- Two registration codes to obtain and display, the CIN and the CIR
- Lower ADR leaves less room for error on costs
London (United Kingdom)
London is a heavyweight by demand, fuelled by year-round tourism, business travel, and limited hotel stock. Listings run at about 71% occupancy with an ADR around €191, and the market’s median annual revenue is roughly €51,000. The most attractive central areas for hosts are Covent Garden, Soho, and Euston, where well designed studios and 1 to 2 bedroom apartments perform best.
The arithmetic is where London stops being simple. Short-term letting of a residential property in Greater London is limited to 90 nights per calendar year without planning permission for a change of use. Ninety nights at the city’s average rate is closer to €17,000 than €51,000. Against a central entry price near €837,000, that is a very different asset from the one the headline revenue suggests.
England’s national registration scheme is still not running. Government confirmed a mandatory approach in February 2024 and then missed an April 2026 target. Guidance updated on 2 October 2026 now expects the register to commence in March 2027. Registration is not a planning permission, so it will sit alongside the 90-night rule rather than replace it.
Benefits for investors
- Global mix of leisure and business guests
- High ADRs in prime central neighbourhoods
- Deep resale and long-term rental market
Risks for investors
- Without planning permission, the 90-night limit puts the headline revenue out of reach for a whole-home let
- Highest entry price and the lowest revenue-to-price ratio in this guide
- Registration scheme and planning rules still unresolved
- High purchase prices and operating costs that compress yield
Bucharest (Romania)

Bucharest is the cheapest capital-city entry in this guide. A typical listing runs at about 64% occupancy, an ADR near €64 and roughly €15,500 in annual revenue, against a central entry price of about €168,000. That puts revenue at about 9% of the entry price, on the lowest revenue of any market here, so cost control decides the result.
The Old Town around Lipscani, Universitate, Piața Romană and the Floreasca and Dorobanți districts draw most short-stay demand. Compact one-bedroom flats close to the metro work best for city-breakers and business guests.
There is no city-wide freeze. A short-term apartment does need a tourism classification certificate from the ministry responsible for tourism, under classification rules updated by Order 948/2026, published in July. The file may also require consent from the owners’ association and neighbours. That consent is often the hardest step in an apartment block. Operating without classification risks fines of up to RON 50,000.
Check one more thing before you buy: the building’s seismic risk class. Romania has banned both short- and long-term rentals in RS1 buildings, its highest-risk category, since 2024. Even so, an investigation published in July 2026 found 207 listings operating in such buildings. A cheap central flat in an RS1 building is not a bargain.
Benefits for investors
- Lowest capital-city entry price in this guide
- No city-wide freeze on new short-term rentals
- Low purchase price leaves room for a renovation budget
Risks for investors
- Lowest occupancy and revenue of the twelve markets here
- Classification certificate and possible owners’ association consent
- Rentals banned in RS1 seismic-risk buildings
- Currency and Romanian tax rules to manage
Malta

Malta is a country-sized market rather than a city, and it earns its place on the numbers. Across Airbtics’ Malta market, a typical listing runs at about 77% occupancy, with an ADR near €130 and roughly €37,500 a year. Against Numbeo’s national city-centre benchmark of about €196,000, that is about 19% of the price, second only to Palermo.
Sliema, St Julian’s and Valletta hold most short-stay demand, with Gozo quieter and more seasonal. English is an official language, which simplifies contracts and guest communication.
First, check whether you may buy to let at all. Non-EU buyers, and EU citizens without five years’ continuous residence, generally need an AIP permit for a secondary home. The tax authority states that AIP property cannot be rented out. For most foreign investors that means the Special Designated Areas, where buying is unrestricted but prices sit outside the benchmark above.
Legal Notice 92 of 2026, published in April, tightened licensing without closing it. A Malta Tourism Authority licence is required, with the licence number and a 24/7 contact on display and a waste plan on file. Units take two guests per bedroom and ten in total, unless they have independent road access, and no booking may exceed 90 consecutive days. Neighbours get no veto under the licensing procedure, though building by-laws still apply. Operating unlicensed brings a three-year disqualification for the operator and the property.
Benefits for investors
- Second-highest revenue-to-price ratio in this guide
- Licences still granted to units that meet the criteria
Risks for investors
- Property bought under an AIP permit cannot be rented out
- National averages hide wide gaps between Sliema and Gozo
- The MTA can refuse units below its finish standard and set local criteria
Cities Where Airbnb Is Legal in 2026
Airbnb itself is legal across Europe. What varies is whether a city will register your property, and that is the question a buyer needs answered. The tables below cover the markets in this guide, plus the closed markets investors still ask about. Each answer is a starting point, because eligibility also depends on the building, the planning position and how the property is transferred.
Markets Still Open to New Hosts
These markets still register new short-term rentals, subject to the conditions shown.
| City | Can a new investor register? | What applies in 2026 |
| Porto | Yes, outside five parishes | 15% containment threshold; Vitória, São Nicolau, Sé, Santo Ildefonso and Miragaia closed |
| Kraków, Warsaw | Yes | Bill passed the Sejm in October 2026 and awaits the Senate; proposed bans from January 2028 |
| Prague | Yes, subject to building-use and operating rules | Comparatively light rules today; eTurista register in preparation |
| Rome | Yes | CIN required since January 2025; in-person or live video guest identification |
| Milan | Yes | CIN; key boxes banned on or facing public land since January 2026 |
| Palermo | Yes | CIN plus Sicily’s regional CIR code; no city cap found |
| Bucharest | Yes | Tourism classification certificate; rentals banned in RS1 seismic-risk buildings |
| Malta | Yes, if the property may be let | MTA licence under Legal Notice 92 of 2026; property bought under an AIP permit cannot be rented out |
Restricted and Closed Markets
In these markets, a standard apartment purchase runs into caps, freezes or planning limits.
| City | Can a new investor register? | What applies in 2026 |
| Valencia | Only where caps allow | 2% of housing per neighbourhood, 8% of beds per population, ground or first floor with independent access |
| Lisbon | Restricted; check the containment category | Absolute zones closed, relative zones only by exceptional authorisation; registration generally lapses on sale in containment zones |
| London | Yes, within the planning position | Whole homes limited to 90 nights a year without planning permission for change of use; national register expected March 2027 |
| Madrid | Rarely | Historic centre: no tourist flats scattered in residential buildings, whole buildings on non-commercial streets on 15-year licences; elsewhere ground or first floor with independent access |
| Athens | No, in the centre | New registrations banned in municipal districts 1, 2 and 3 to 31 December 2026 |
| Thessaloniki | No, in the centre | New registrations frozen in the first municipal community from 1 July to 31 December 2026 |
| Budapest | No | City-wide moratorium on new registrations to 31 December 2026; District VI banned outright from January 2026 |
| Barcelona | No | City plans not to renew roughly 10,000 tourist apartment licences when they expire in November 2028 |
What Changed in Madrid, Athens and Budapest
These closures deserve a note each, because investors still meet these cities on older lists.
Madrid’s Plan RESIDE received final approval from the Comunidad de Madrid on 27 August 2025. In the historic centre it bans tourist flats scattered through residential buildings, even on the ground floor. On non-commercial streets, a whole residential building can be turned over to tourism on a 15-year licence. Elsewhere, new tourist flats need independent access from the ground or first floor, and fines for unlicensed operation now start at €30,001.
Athens stopped accepting first-time registrations in its first, second and third municipal districts from 1 January 2025. The freeze now runs to 31 December 2026, and central Thessaloniki joined it on 1 July 2026. Existing registrations may continue while the property stays with the same owner. Since 1 July 2026, selling or gifting a registered property in these zones removes it from the registry. The new owner cannot re-register while the freeze lasts. Penalties start at 50% of the rental income earned since January 2025, with a €20,000 minimum.
Budapest has run a city-wide moratorium on new registrations from 1 January 2025 to 31 December 2026. It also raised the annual flat tax per room for individuals using the itemised tax option from HUF 38,400 to HUF 150,000. In Terézváros, District VI, apartment-style short-term accommodation has been banned outright since 1 January 2026. If you are buying a flat that already operates, confirm with the district office whether the moratorium lets you register as the new provider.
The EU Registration Rule
One rule now sits above all of them. Regulation (EU) 2024/1028 has applied since 20 May 2026. Wherever a registration procedure applies, platforms must collect the number before a listing goes live. They must also display it, spot-check it, and pass activity data to the authorities. An unregistered listing in such a market is no longer a quiet risk. It is a listing the platform is expected to find.
Best Countries for Airbnb Investment in Europe
City data shows where the money is. Country data shows which legal system you are buying into, and in 2026 that is the more durable question. For markets beyond Europe, see our guide to the best Airbnb markets worldwide.
Portugal still mixes strong demand with workable rules, if you treat its two cities separately. Decree-Law 76/2024 ended the national registration freeze and the five-year expiry, and municipalities now set containment, more gently in Porto than in Lisbon.
Italy is relatively predictable. Core rules are national, Rome earns the second-highest revenue here, and Palermo shows the highest revenue relative to price. The catch is business treatment from the third short-let apartment.
Poland has low entry prices but is mid-reform. If enacted, the October 2026 bill adds registration and possible local bans from 2028, and a whole building escapes a condominium vote but not a municipal zone.
Czechia has light rules and high occupancy, but Prague’s central prices sit closer to Rome’s than to Kraków’s, which caps the ratio.
Spain is no longer one market. Regional and municipal rules decide most outcomes, and since April 2025 a new tourist flat in an apartment building needs a three-fifths community vote.
Greece is open outside its frozen zones in central Athens and, since July 2026, central Thessaloniki, where a sale or gift also ends the registration.
The United Kingdom offers high nightly rates and, in London, a tight planning limit on using them.
Malta kept licensing open after its 2026 overhaul, provided the property was bought on terms that allow letting.
Romania and Bulgaria are the frontier, with low entry prices but thinner demand and shallower resale markets.
Risks and Challenges for Airbnb Investors in Europe
Even the best European cities for Airbnb present meaningful risks. First, rules can change quickly. Cities may add day limits, new reporting, or tougher safety checks, so an investor must watch legislation and keep full compliance.
Second, income depends on travel cycles. Shocks, crises, or airline cuts can damage demand and leave high-cost units with low yield. Over-supply in one neighbourhood can also push down prices and increase vacancy.
Third, operations matter. Remote owners must rely on local partners for key handling, cleaning, and guest support, and weak management can damage reviews and revenue. Currency swings, tax audits, and complex cross-border rules can also affect net results.
Fourth, and specific to this moment, a licence is not always an asset. Lisbon’s containment rules show that a registration can attach to the current owner rather than to the property. Poland’s proposed 2028 provisions show that a neighbour vote may one day end a business that was fully compliant when it started. Build both possibilities into your exit assumptions, not just your optimistic case.
FAQ
1. What is the best place to buy Airbnb property in Europe right now?
On the numbers here, Palermo and Malta show the most revenue relative to entry price, and Valencia leads the mainland cities on that measure. Rome earns the most among large cities without a night cap. Treat those as starting points, not returns. Palermo suits a smaller budget if you accept thinner data, and Malta a buyer who can purchase where letting is allowed. Rome suits a buyer who prefers national rules, and Porto one who wants a major city under €250,000. Always confirm that your specific street or building is still open to new registrations before you offer.
2. How much can I earn from Airbnb properties in Europe?
In the markets covered here, a typical listing brings about €15,500 to €51,000 in gross annual revenue, cleaning fees included. Results vary by city, neighbourhood, seasonality, property quality and guest reviews. High-demand capitals and prime centres sit at the upper end, while secondary markets and average listings earn less. Your final outcome also depends on local regulation, operating costs such as cleaning, maintenance, management fees and utilities, and how efficiently you manage pricing and occupancy. Where a night cap applies, as in London, model the capped figure rather than the market average.
3. How much money do I need to start investing in Airbnb in Europe?
On the benchmarks used here, a 50 m² central unit runs from roughly €117,000 in Palermo to about €837,000 in central London. Add purchase taxes, notary and legal fees and furnishing, which vary widely by country and buyer status. Bucharest and Malta’s national benchmark sit below €200,000, Kraków and Valencia near €247,000. If you use a mortgage, add the down payment, financing costs and a reserve for vacancy, repairs and any future regulatory changes.
4. Which European cities have banned new Airbnb registrations?
Four markets restrict new tourist flats in different ways. Madrid uses zoning in its historic centre, Athens and Thessaloniki use central freezes, and Budapest runs a city-wide moratorium. Barcelona plans not to renew its roughly 10,000 tourist apartment licences when they expire in November 2028. The Greek and Budapest freezes are set to run to the end of 2026, and Athens has already extended its once. Existing flats can generally keep operating in Athens while they stay with the same owner, and in most of Budapest, though not in District VI.
5. What is the difference between short-term and medium-term rent for investors?
Short-term rent (stays under about 30 to 90 days) targets tourists and business travellers, offers higher nightly rates and potentially higher yield, but needs intensive cleaning, guest support and strict licence compliance. Medium-term rent (roughly 1 to 6 months) focuses on students, digital nomads and relocating professionals, with lower nightly pricing but longer stays and simpler operations. In capped or contested markets, many investors now underwrite the medium-term case first and treat short-term upside as a bonus.
6. Do I need a local company or can I invest as an individual?
In most European countries, you can invest either as a private individual or through a local company. Many small investors simply buy in their own name and report rental income according to local and home-country tax rules. However, people who own several properties or have higher income sometimes use a company to keep business risks separate from personal assets and to manage taxes more efficiently. Because rules and tax treaties differ between countries, it is best to confirm the right structure with a local tax advisor before you buy.
7. How can I reduce the risks associated with changes in legislation?
You can lower legal risk by choosing flexible strategies and compliant assets. Prefer locations where you can switch from short-term to medium- or long-term rentals if rules tighten. Before buying, verify zoning, licence conditions, building regulations and any night caps, and confirm whether the registration transfers with the property. Use conservative financial forecasts so your project survives stricter limits. Finally, follow local news, owner associations and professional advisors so you can react early when new regulations appear.
Final Words
The best place to buy Airbnb property in Europe in 2026 is where demand, price and permission line up at the same time. Permission is the new variable. A city can have excellent occupancy, a healthy nightly rate and a liquid resale market. It can still be closed to the one thing you need it to do. Remember that this article is for information only and does not replace personal financial or legal advice.
If you treat each property like a small business, track your numbers, and plan for taxes, expenses, and local rules, you can improve both stability and growth. When the day-to-day of running a listing abroad is the part you would rather not own, that is exactly what professional Airbnb management is for.